The short answer: Yes, but a 1099 form only shows what you were paid. Lenders qualify you on net business income after expenses, usually with a two-year history. Fannie Mae and Freddie Mac have narrow exceptions for shorter histories, and some Non-QM lenders offer 1099 programs with their own rules. Nevada has no state income tax, but you still need federal tax records.
This post is for you if:
- You are an independent contractor, freelancer or gig worker in Las Vegas.
- You earn tips or commission and are not sure which rules apply.
- You want to know whether your 1099s alone can qualify you.
Not sure how a lender will count your income? Tell me how you get paid and I will help you gather the right paperwork.
Book a free callDoes a 1099 count as income for a mortgage?
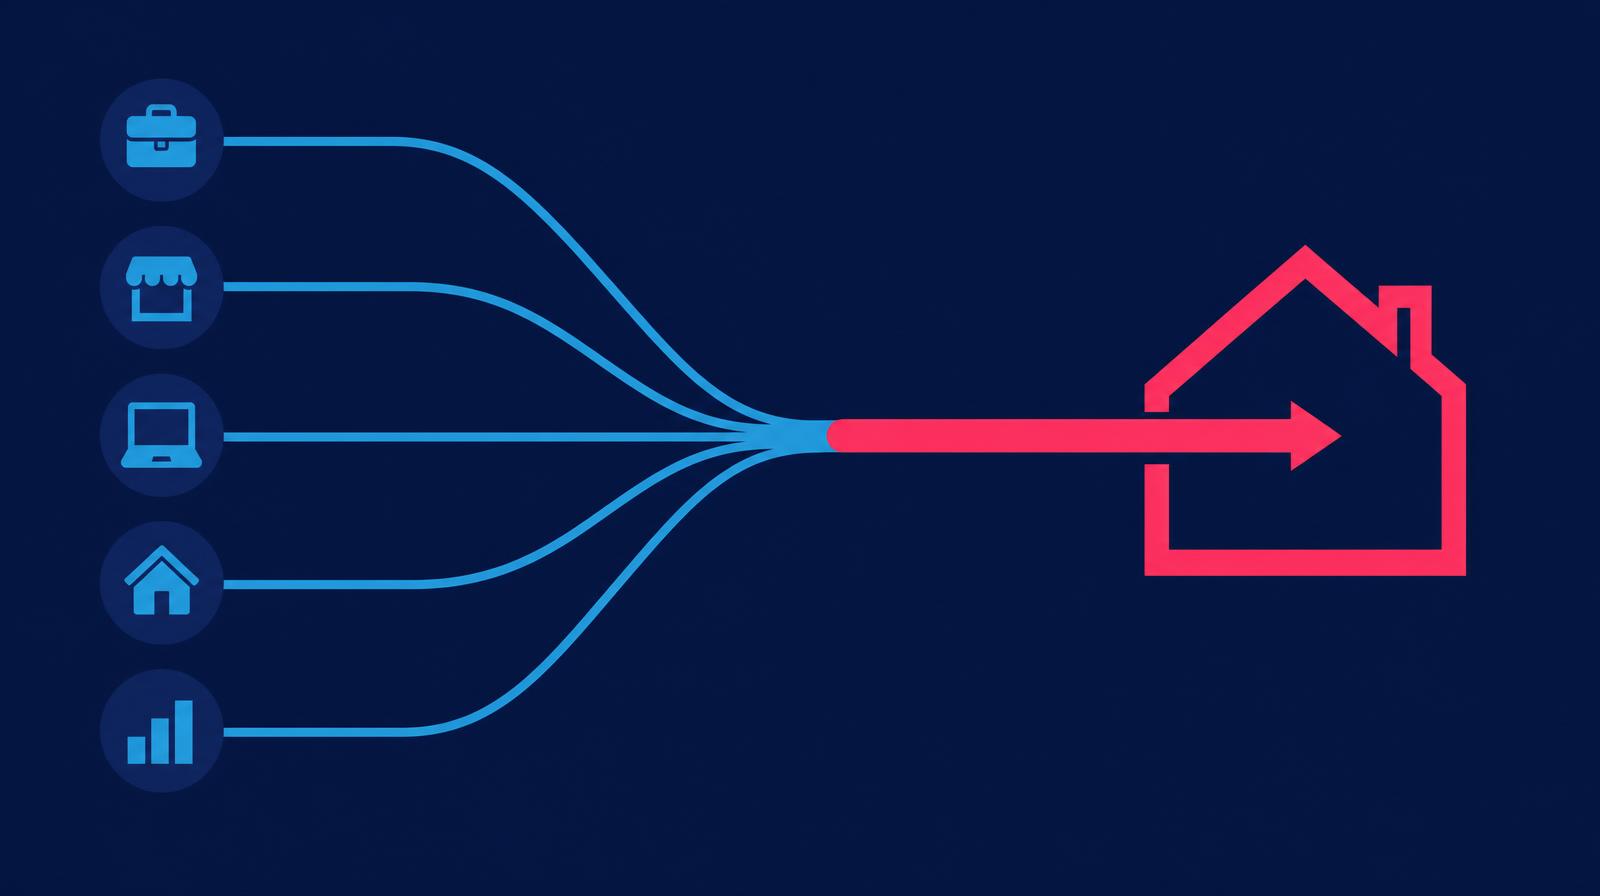
It counts as proof of payments, not as qualifying income. The IRS says an independent contractor is generally self-employed and reports nonemployee compensation on Schedule C. Lenders then look at what is left after business expenses.
Fannie Mae focuses on earnings trends and the actual source of the income. It adjusts Schedule C cash flow by adding back some recurring items and deducting nonrecurring income. That is why two people with the same 1099 total can qualify for different amounts.
What is the two-year rule, and are there exceptions?
Fannie Mae generally wants a two-year history of earnings. If you have been self-employed under two years, it may consider 12 months in the current business plus prior earnings at the same or higher level in a related field or similar job. Freddie Mac has a bulletin for contractors on 1099s that also calls for a two-year history, with a documented 12-month exception and tests on your Schedule C. In June 2026 Freddie removed its lesser-of-income test for some borrowers with at least two combined years in current self-employment and similar prior work, and the other requirements continue.
Two years is the norm. Lenders can add stricter rules, so never assume an exception applies to you.
What if you earn tips or commission?
Employee tips and commission follow a different path than 1099 self-employment. Fannie Mae accepts IRS Form 4137 with two years of returns for tips an employer did not report. The IRS says self-employed tips go on Schedule C as business income. Tell your loan officer which one you are, because the paperwork changes. See my guide for 1099 and tipped income.
Want to see which route fits your income? Book a free call and bring your last two years of returns.
Book a free callWhat about Non-QM 1099 programs?
Some lenders offer their own 1099 programs outside Fannie Mae and Freddie Mac. As lender examples only, NASB says it reviews the last 12 months of 1099-NEC income plus year-to-date records, but its fine print requires a two-year history in the same line of work. Angel Oak allows one or two years of 1099s plus year-to-date records and also requires two years in the same line. Posted minimum loan sizes, credit scores and down payments differ, and I did not verify Nevada availability. Ask for the current written terms.
Non-QM loans can be riskier or more expensive, according to the CFPB. Regulation Z still requires a good-faith ability-to-repay review for covered loans. If your deposits are the better story, read my bank statement loan guide.
How should you prepare?
- Separate W-2 income from contractor income.
- Gather two years of tax returns with all schedules, plus 1099s and year-to-date records.
- Keep business and personal accounts clean and consistent.
- Do not make large unexplained deposits or take on new debt before you apply.
- Ask the lender which method it will use and how it will calculate your income, in writing.
CFPB says self-employed borrowers need more extensive income documentation, and requirements vary by lender. Nevada's lack of a state income tax does not remove federal documentation. See my self-employed loan page too.
Frequently asked questions
What is a 1099 mortgage loan?
It is a Non-QM program from some lenders that uses 1099 income and year-to-date records. Terms are set by each lender.
Can I qualify with only 12 months of 1099 income?
Sometimes, with narrow exceptions or certain Non-QM programs. Many require two years in the same line of work.
Do write-offs affect qualifying?
Yes for tax-return programs. Lenders analyze Schedule C cash flow after expenses.
Can gig work income be used?
Often, if it is documented and stable. The method and history required vary by lender.
Does Nevada having no income tax help?
It does not change federal return and documentation rules.
Sources
Last verified October 28, 2026. Programs, limits and fees change, so confirm the current numbers before you rely on them.
- IRS: Form 1099-NEC and independent contractors
- Fannie Mae B3-3.5-01: Self-employed borrower
- Fannie Mae B3-3.6-03: Schedule C
- Fannie Mae B3-3.3-02: Tip income
- Freddie Mac Bulletin 2022-18
- IRS: Tip recordkeeping and reporting
- CFPB: Gather and update your paperwork
- NASB: 1099 mortgage loan
- Angel Oak: 1099 income loan program
- 12 CFR 1026.43 (eCFR)
- Nevada Department of Taxation: Income tax in Nevada
Ready to see what you could qualify for? Book a free call.
Book a free callI am Fabion Medhanie, a retired U.S. Army Captain and mortgage broker in Las Vegas. This is education, not a rate quote or a loan approval. Your loan options depend on your full file.
Based in Las Vegas? Meet a veteran-led mortgage broker in North Las Vegas, or see VA loans and all loan options.