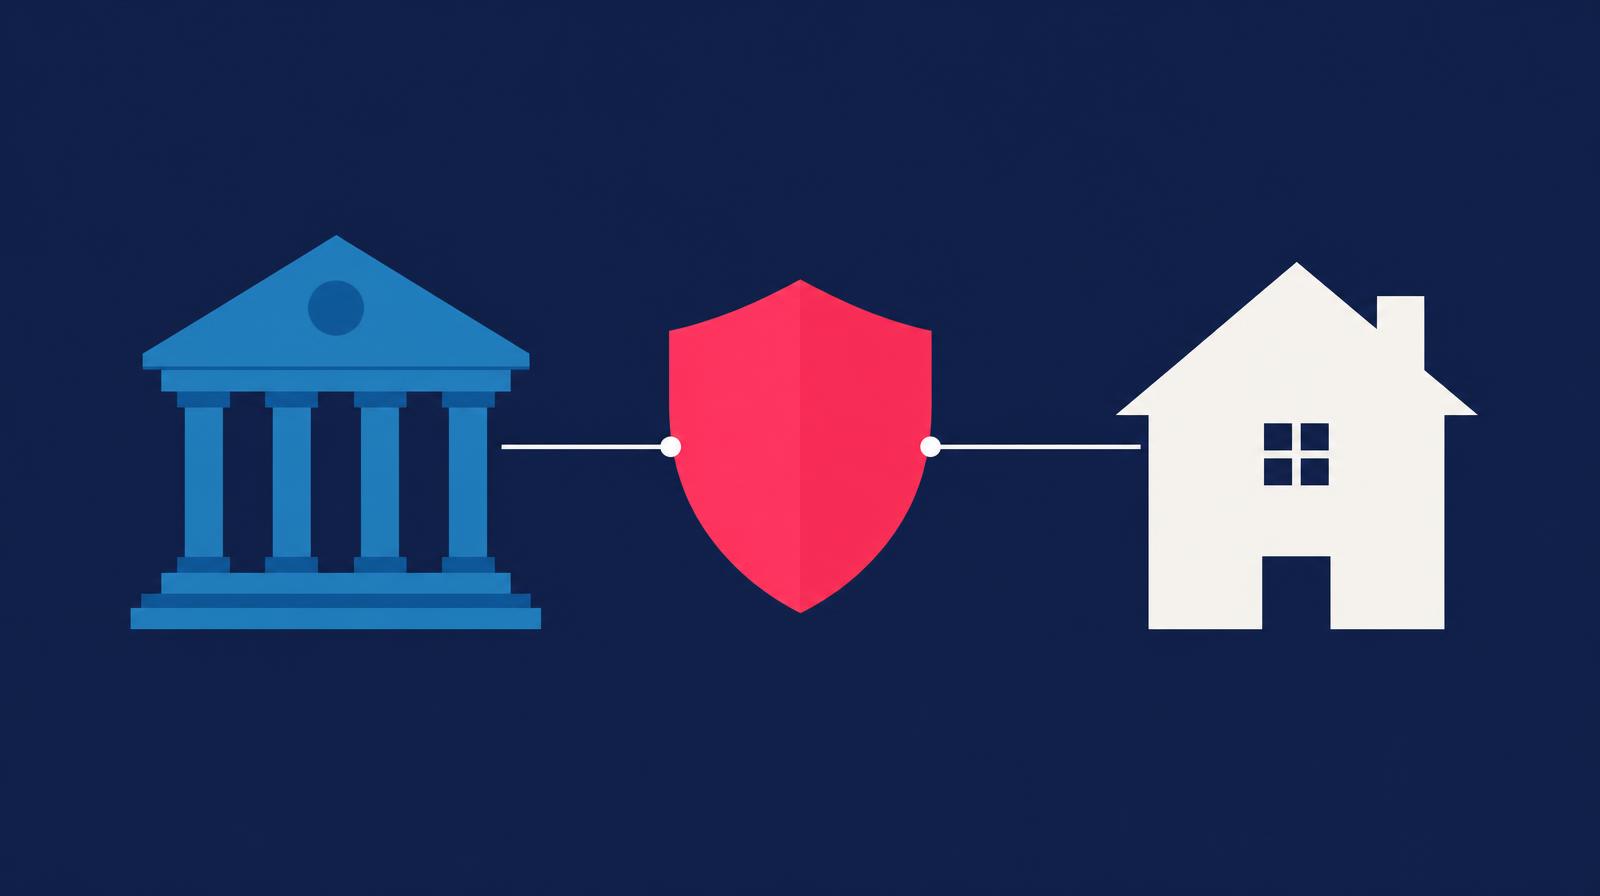
The short answer: An FHA loan is a mortgage made by an FHA-approved lender and insured by the Federal Housing Administration, an agency within the U.S. Department of Housing and Urban Development (HUD). FHA insures the lender's loan; it does not make the mortgage directly to you.
This post is for you if:
- You are comparing FHA financing with other ways to buy a home
- You want a clear picture of down payment, credit score and mortgage insurance basics
- You plan to occupy the home and want to understand the first steps
Would it help to talk through whether the FHA basics fit what you are planning for a home purchase?
Book a conversationWhat is an FHA loan?
An FHA-insured mortgage comes from an FHA-approved lender. The Federal Housing Administration (FHA), part of HUD, insures eligible loans made by those lenders rather than lending directly to homebuyers. HUD explains FHA's role.
That insurance protects the lender against losses if a borrower defaults; HUD collects premiums from borrowers through lenders. It is not a promise of approval or a release from repaying the loan.
How does an FHA loan work, step by step?
FHA financing follows a lender-led process: you apply with an FHA-approved lender, the lender reviews your finances and the home, and the eligible mortgage is closed and insured under HUD rules. The steps below show where lender decisions and FHA requirements fit.
| Stage | What happens |
|---|---|
| Talk with a lender | Discuss the home, location and whether an FHA purchase loan may fit. |
| Apply and share documents | The lender reviews credit, income, assets and debts. HUD requires applicable monthly liabilities to be included in the qualifying ratio. |
| Review the property | The lender arranges an appraisal and checks applicable FHA property requirements and loan limits. |
| Underwrite and close | The lender evaluates the complete file, may request more information, then closes an approved loan and completes FHA insurance steps. |
This is a basic flow, not a promise about timing or approval. HUD Handbook 4000.1 sets the lender's FHA processing and underwriting rules.
If you are weighing FHA against another option, what part of the numbers would you want to understand first?
Talk it throughWhat credit score and down payment do you need?
HUD's standard credit tiers set maximum financing, not approval. A score below 500 is ineligible; scores from 500 to 579 are capped at 90% loan-to-value (LTV); a score of 580 or higher may qualify for maximum financing. For standard purchases, HUD allows up to 96.5% LTV and at least 3.5% minimum required investment.
The 3.5% minimum is not the same as total cash needed to close. HUD describes FHA as a low-down-payment option. A lender also reviews income, assets, debts and the property, including applicable monthly liabilities in the qualifying ratio. For a deeper checklist, see my FHA loan qualifications guide.
Does an FHA loan require you to live in the home?
For a standard FHA purchase, at least one borrower must occupy the home within 60 days of signing the security instrument and intend to live there for at least one year. HUD notes that 203(k) rehabilitation products may have different occupancy timing.
If your plan is to buy a rental or second home, confirm the intended use and program rules with a lender before choosing a loan. HUD's Handbook gives the standard occupancy rule.
What mortgage insurance do FHA borrowers pay?
Most FHA mortgage programs charge an upfront mortgage insurance premium (UFMIP) of 1.75% of the base loan amount, plus annual MIP billed monthly. HUD says the annual rate depends on loan-to-value, base loan amount and term.
HUD's current Handbook chart lists annual rates from 0.50% to 0.75% for terms over 15 years, and from 0.15% to 0.65% for terms of 15 years or less. Those are rate bands, not your quote. Ask the lender to show your premium and duration. Mortgagee Letter 2023-05 gives the annual MIP schedule.
For more on FHA mortgage insurance, see my FHA mortgage insurance guide.
How do FHA loan limits work?
FHA loan limits cap the mortgage amount FHA will insure and vary by area and property size. HUD updates limits annually using county or metropolitan statistical area (MSA) home-sale data, so check the limit for the home's location and size.
Use HUD's FHA Mortgage Limits lookup and select the property's state, county or MSA. HUD's 2026 limits announcement explains the annual calculation. I am not listing a county amount because the correct figure depends on location and property size.
How do you decide whether an FHA loan fits?
An FHA loan may fit when its down-payment and underwriting features match your plan, but I compare the full payment and cash needed instead of judging by one requirement. Ask the lender to show actual terms, mortgage insurance and closing costs before you choose.
Compare FHA with other financing available for your situation. If you are buying in Nevada, start with my FHA loans in Nevada overview. If another question matters most, we can work through that first.
Frequently asked questions
Does FHA lend directly to buyers?
No. An FHA-approved lender makes the mortgage; FHA insures eligible loans.
Can I buy with a low down payment?
HUD lists low-down-payment financing, but your credit tier and full file determine eligibility.
Does meeting a credit tier mean approval?
No. A lender reviews credit, income, debts, assets, property and program rules.
Does FHA mortgage insurance include an upfront charge?
Most programs have upfront and annual MIP; the annual premium is paid monthly.
Can a standard FHA purchase be a rental?
The standard purchase rule is principal-residence occupancy; confirm exceptions with a lender.
Where do I check FHA limits?
Use HUD's lookup and select the home's location and property-size category.
Sources
Last verified October 29, 2026. Programs, limits and fees change, so confirm the current numbers before you rely on them.
- FHA History, U.S. Department of Housing and Urban Development
- FHA Loans, U.S. Department of Housing and Urban Development
- Single Family Housing Policy Handbook 4000.1, Update 18, HUD
- Mortgagee Letter 2023-05, HUD
- FHA Mortgage Limits lookup, HUD
- HUD's Federal Housing Administration Announces 2026 Loan Limits
If you are ready to organize the details, start your application here and we can review your options with the full picture in view.
Start your applicationI am Fabion Medhanie, U.S. Army Retired and a loan officer in Las Vegas. This is education, not a rate quote or a loan approval. Your loan options depend on your full file.
Buying or refinancing in Nevada? See FHA loans in Las Vegas and Nevada and the guide to Nevada down payment assistance.